Monday, 24 February 2014

Worldwide Security Printing Market to reach $35.3 billion by 2018

Global security printing will grow at a CAGR (compound annual growth rate) of 6.3% for the ten-year period between 2013 and 2018, divided into a 6.7% CAGR for 2008-13 and 5.9% for 2013-18 according to a new market report by Smithers Pira.

The Future of Global Security Printing to 2018 contains an in-depth five year forecast of this fast-moving market. The report examines key conditions driving and prohibiting past and future growth across nine technology categories, five end-use markets and eight geographic regions.
Counterfeiting continues to affect society at an alarming rate - criminal organisations, petty criminals and amateur forgers unabatedly attempt and succeed in the trade of producing fake ID documents, passing counterfeit bank notes, invading supply chains with altered goods and packaging, and illegally copying tax stamps. Security printing, along with law enforcement, helps to deter counterfeiters and detect forgeries, but is increasingly affected by the digitisation of society and products.
According to the report, digitisation and convergence are two megatrends that the security printing industry needs to come to terms with. They can be seen as a threat jeopardising the very existence of the industry, or as an opportunity to innovate and evolve in order to address risk in a broader context. In the near foreseeable future, however, security printing will continue to fulfil its critical role of preventing and detecting alterations, forgeries and copies, and support product authenticity.
In geographical terms, Asia represented almost 50% of the global market for security printing in 2013, according to The Future of Security Printing to 2018. This is hardly surprising, as the region holds over 55% of the global population. Western Europe, Eastern Europe and both of the Americas each held 10% or just under.

Figure E.6 Global market for security printing by region, 2013 (%)
Global Markets for Security Printing to 2013
Source: Smithers Pira
Figure E.7 Global marker for security printing by region, 2018 (%)
Global Markets for Security Printing to 2018
Source: Smithers Pira
Western Europe, North America and Australia - arguably the most industrialised regions, were most impacted by the global financial crisis in 2008-13, but are also predicted to be rebound the strongest in the years from 2013-2018. The growth rate for each of these regions is at least twice as high in 2013-18, than what it was during 2008-13.
The study states that security printing growth in the financial end-use market will slow down to a CAGR of 5.5% as the use of cash worldwide decreases, either by consumer-driven substitution to other forms of payment, or by government-driven incentives. The Personal ID end-use market shows the largest decrease in growth, from an 8% CAGR in the 2008-13 period to a mere 3% CAGR for 2013-18. Even though National ID projects will still take place from 2013-18, the number is expected to be smaller than in the previous five years, and ePassport projects have shifted to maintenance mode. High growth is projected for the Brand Protection end-use market as a result of recently published ISO standards for security features and worldwide legislation mandating various forms of ePedigrees.
The Future of Security Printing to 2018 is available now for £3,950. To find out more about the report and how your company can benefit from a global usage licence, please contact: Heather Adams (US) T: +1 207 781 9632 or Bill Allen (UK) T: +44 (0)1372 802086.

Monday, 17 February 2014

Insight: The Top Four Personal Care Packaging Trends

From skincare to fragrance and from bath products to oral hygiene, consumers are continually changing the way they interact with and discard their personal care products. Whether you're a manufacturer or a product marketer, you know how important it is to stand out from the crowd whilst also reflecting the changing needs of the consumer with your packaging. 
In our new bulletin, Smithers Pira explores the top four personal care packaging trends you need to know about to make sure your products stay ahead of the curve.

1.) Sustainability

Consumers are becoming more environmentally aware and these concerns are leaking into their personal care purchases. These days, consumers are actively seeking out signs on packaging that show the manufacturer has an environmental conscience. Understanding how this commitment to sustainability can be communicated on packaging is increasingly key to attracting consumers. 
However, herein lies the challenge for a large portion of the personal care market. Luxury products, relying on the perception of exclusivity and prestige for sales, experience a potential disconnect here as brand owners often do not want to associate their high-end goods with recycled materials. An example of a company successfully balancing these two concerns is luxury packaging producer Toly Products Ltd, and their new Zeta Biozone range. Optionally available in two environmentally friendly materials, PLA and Eastman's Tenite cellulosic polymers, Zeta Biozone are able to satisfy varying groups of consumers without losing its luxurious image.

2.) Convenience

A growing number of consumers balance their personal care routines with increasingly busy lifestyles, meaning that products offering ease of use are most likely to succeed.
As a result, there is a general movement towards PET (polyethylene terephthalate) usage, which allows for product flexibility on-the-go. Manufacturers are also using gravity to ease dispensation, a technique which has been adopted across the board. 
Easier to open caps, closure devices, packs which stand up better in the shower, portion control devices and 'handleability' are all innovations which are responding to a consumer's desire for convenience and ease of use. For example, Unilever's Lynx Detox Deep Clean Shampoo features an innovative button operated cap, designed for speed and ease of use in the shower.

3.) Male grooming

The growing popularity of male grooming, particularly in emerging markets, is increasing the global demand for male hair care and facial skin care products. Shaving, aftershave and antiperspirants have been the traditional products most in demand by men, and these items are now being joined by a plethora of skin and hair care products. This trend is usually driven not so much by a desire for attractiveness, but by a professional or social situation coupled with a desire to proclaim one's status or differentiate oneself from the crowd. 
Therefore in this new, tentative market, branding attributes hold significant value. The importance of building brand affinity as well as awareness and loyalty feature heavily in the brand owner's marketing activities as consumers look for the reassurance of established brands for their daily personal care routines.
Preservation of quality is a packaging pre-requisite to ensure the product remains fit for purpose for the duration of its use. Pack functionality is also very important in this sector, as the time-poor male consumer looks for more practical and simple application from their packaging. Ergonomics can also act as a differentiator to support and build the brand during product usage. 

4.) Value-added products

As new developments continue to occur in the fast-moving personal care packaging sector, consumers are increasingly expecting added value in the cosmetics they purchase. Packaging companies should meet this expectation through the addition of innovative techniques, such as integrated applicators. 
Across all categories, these dispensing systems have become a key way for brands to differentiate products and offer consumers additional value. Brands are introducing products with dispensing applicator tips that directly apply formulas to the face or other target area, including items such as sponges, brushes and roll-ons. Applicator tips have found their way into many different beauty segments, with skincare being one particularly suitable application.
Aptar's Caresse applicator is a leading example of such an applicator. A bi-injected, flexible applicator that works like a fingertip, the Caresse provides a gentle application which also massages the skin.
If you need to know more about consumer packaging trends, our full, comprehensive report, The Future of Personal Care Packaging to 2018, is available for purchase at just £3950. 

Monday, 10 February 2014

Bioplastics share of packaging sector to grow from 0.2% in 2013 to 2.4% by 2023

Driven by both biorenewability and biodegradability trends, the demand for bioplastics in packaging is expected to reach 535,000 tonnes and grow to about 9.45 million tonnes by 2023. This represents a global CAGR of 33%, according to a new study by Smithers Pira.
The Future of Bioplastics for Packaging to 2023 provides an in-depth look at this industry throughout the coming decade. Containing key details about end use markets, regional variance and supplier opportunities, the report also offers forecasts of technology development in this exciting area.
According to the report, worldwide consumption of all polymers is valued at more than $650 billion in 2013. In geographical terms, North American and European global shares are both slightly under 25% each, while Asia (including Japan) represents about 40% global share. The remaining 13% share is consumed in other regions. By 2023, the Asian share of global biopolymer demand is expected to increase to 34%, while both Europe and North America decline in share of global packaging demand for this type of material.

This general shift towards bioplastics is driven by both environmental concerns and the increasing costs for fossil fuel products. Growth is closely linked to the relative competitive prices for traditional polymers (petro-polymers) based on fossil fuel products such as oil, natural gas and derivatives. Therefore, bioplastic acceptance and growth in packaging are driven by the dynamics and economics of the fossil fuel industry on a global basis.
As biorenewable resources, including all forms of biomass, become an increasingly important raw material and energy source, biomass conversion refineries will broaden the technology and provide chemical feedstocks, some of which will be converted to biopolymers.
According to The Future of Bioplastics for Packaging to 2023, bioplastics are finding a new and welcoming audience in the packaging industry. This is driven by higher energy costs and new understandings about environmental sustainability. Indeed, biopolymers will find future success and grow in demand as society is increasingly forced to cope with higher energy costs and consumers recognise that a reduced carbon footprint is good for business and the environment.
The majority of biopolymer end-use has been in packaging and food service non-durable applications. Such applications are often designed for one-time use, and might ordinarily end up in landfill or floating in the ocean. For this reason, biodegradability was considered to be the most important driver. However, this has become less of a focus in recent years as it represents a too wasteful end-of-life option. According to the report, the focus is now on bio-based products that are considered sustainable and renewable through feedstocks that are grown, and end-products that are recycled.
The Future of Bioplastics for Packaging to 2023 is available to purchase online and receive immediately for £3950.
To find out more about the report and how your company can benefit from a global usage license, please contact: Heather Adams (US) T: +1 207 781 9632 or Bill Allen(UK) T: +44 (0)1372 802086.

Thursday, 6 February 2014

Discussion: How does Sustainability Challenge Luxury Packaging?

Consumers are becoming more environmentally aware and are seeking out more sustainable lifestyle choices, as discussed in our recentconsumer packaging trends bulletin. Packaging manufacturers are responding by ensuring their materials and processes are as eco-friendly as possible.
But how about luxury packaging trends? There is increasing public and industry pressure on luxury brand owners to reduce the environmental impact of packaging. These implications have meant many luxury packaging companies have obtained Sustainable Packaging Coalition status, and use more environmentally friendly materials such as paperboard, rather than plastics. 
However, is there such a thing as responsible luxury, or does that defeat the point of products designed to be extravagant and superior? As part of our new bulletin series, Smithers Pira explores the potential obstacles involved with sustainability for the luxury packaging industry, and how these are being overcome. 

Why does the idea of "responsible luxury" pose a problem?

Prestige brands and their customers are often more concerned about the look rather than the eco-friendliness of packaging. Customers' expectations for luxury packaging are much different from the general market, with packaging seen as an important part of the product itself. From cosmetics to confectionary, the entire basis of these products is centred on multi-material packaging which contributes to the overall feeling of 'luxury'. Therefore, much of this type of packaging includes metallised plastic, metallised glass and many other types of materials; which, while connoting quality and expense, are very difficult to recycle.
The task of producing environmentally friendly packaging that is also luxurious is therefore a challenging one. Responsible packaging means a whole host of new issues for the luxury packaging market, such as practicality, cost, material choice, aesthetics and maintaining brand image. Due to any one of these reasons, it has often been the case in the past that sustainable packaging solutions have been dropped halfway through the process. 

What is currently being done to make luxury packaging more sustainable?

Despite the various issues involved, in recent years there has been a move towards more sustainable practices in the luxury packaging market. International fashion brand Gucci, for example, launched 100% recyclable packaging with FSC (Forest Stewardship Council) Certified paper back in 2010. However, do customers really care about sustainability when purchasing luxury packaging? Is this move towards sustainability for the luxury sector a genuine move or a passing fad? 
According to research undertaken by Greenwise Business, 47% of the 200 branding and marketing professionals researched felt that Gucci's initiative to cut down on excess packaging was a true reflection of the industry's environmental concerns and its future direction. 
In fact, a number of manufacturers are actively and continually developing luxury packaging solutions which are more sustainable. For example, Meadwestvaco have introduced a more lightweight paperboard Promina® for their tobacco packaging. This new material has a reduced weight ratio of up to seven percent when compared to their PrintKote® Tobacco paperboards, making it a more sustainable solution that can improve converting performance. 
In addition to materials, companies are taking measures to make their entire manufacturing processes more eco-friendly. For example, Crown Cork state they are using fewer resources and using less energy when producing their items; ultimately, 'doing more with less'. They credit this success partly to the intrinsic benefits of aluminium and steel, which are the primary materials they use to make their products. Similarly, the Ardagh Group claims that it identifies, controls, measures and reduces its manufacturing processes and impact on the environment. Manufacturers have therefore made an effort to reduce their environmental impact through the processes they employ, which is definitely a leap in the right direction. 

What are the next steps?

Ways in which companies can continue to improve the eco-friendliness of packaging is to use fewer ink colours to achieve designs, and focus more on the properties of their board with regard to weight and whiteness levels. Bioplastics are being discussed by luxury brand owners, package designers and converters, but to date there are only a few examples of these materials being used for luxury packaging because of their relatively high cost.
Companies can also maximise the use of metal in their products. A current concern for the luxury packaging industry is that some brand owners are now increasingly replacing eco-friendly metal with plastic, particularly in the confectionary and spirits markets. This removes connotations of luxury and also compromises the environmental credentials of the product.
Meanwhile, metal's low carbon footprint is derived from its high recyclability rate, and has the potential to be recycled an infinite number of times without molecular degradation or loss of structural integrity. Metal is the most commonly recycled of all household materials - almost three quarters of metal packaging is recycled in Europe. 
Crown Specialty Packaging Europe's use of metal directly challenges the theory that sustainability credentials should be 'hidden' on luxury packaging to retain connotations of prestige. The metal tins they produced for Nicolas Feuillatte champagne have a printed recyclability message to demonstrate the brand's commitment to sustainable development. Another factor largely unique to sustainable, luxury metal containers is their potential reuse around the home once contents have been consumed. Crown saw the potential in using tins for storage or display when creating, striking, elegant metal containers for Lambertz' Luxury Best Selection biscuit brand. 
According to Veronique Curulla, European Marketing Manager at Crown Specialty Packaging Europe, "Metal packaging, along with the various decorative techniques available, gives luxury brands the twin benefits of dazzling impact and environmentally-friendly appeal. It actually enables the two factors to work together - forming part of a consistent, high-quality brand image." 
While producing cosmetics products in metal tins, paperboard cartons or thin glass jars may be good for the environment, marketing to an industry centred around image, especially when it comes to luxury products and brands, requires careful handling. Manufacturers need to provide luxury packaging companies with packaging that looks as though it is contributing to the often enormous suggested retail price of the product, yet also has some environmental responsibilities. 
So, is green the new colour of luxury or should sustainability be a hidden component of luxury packaging? Have your say by following us on Twitter. 
If you need to know more about the luxury packaging market, purchase our in-depth market report, The Future of Luxury Packaging to 2015 for more of an insight into the future of this industry.

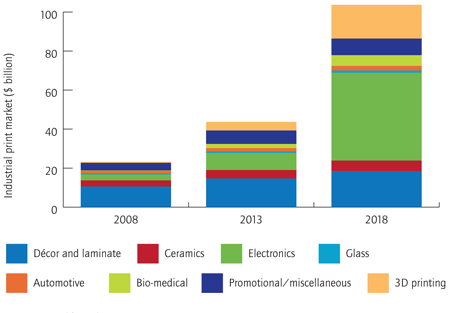
Industrial Printing market to reach over $103 billion by 2018

Industrial printing is sized at $43.7 billion in 2013, after growing at an average CAGR of 13.4% annually from 2008-13. This market is set to accelerate even more in coming years, according to a new market report by Smithers Pira. Part of this rise is due to a widespread economic recovery spurring demand for construction and new car sales, but the capability of new technology in biomedical applications, displays and electronics is also very important.
The Future of Industrial Decoration and Printing to 2018 provides a comprehensive five year forecast of the global industrial decoration and printing industry, containing details of regional markets and trends in addition to various applications and end uses.
Industrial print is used to produce décor and laminated surfaces, ceramics, glass, automotive applications, many promotional/miscellaneous items and many electronic products. Numerous research groups are exploring printed electronics and bio-medical applications, which are steadily gaining traction and coming to market.
However, according to the report, it is not all good news in electronics. Several high profile companies using print to make photovoltaics have ceased trading, but display and lighting are performing particularly well. There is also the rapidly developing 3D printing, which is widely used in the design of many items, and increasingly as a manufacturing technique in its own right for complex objects and small bespoke medical devices such as dental implants and hearing aids.
Figure E.1 Industrial Printing market by product application 2008-2018 ($ billion)

In terms of individual sectors, printed décor and laminates, including flooring, is the largest. However growth rates are at the low end as the sector is mature; one of the leading players, the Formica Corporation, celebrated its 100th birthday in 2013.
In the five years to 2013 bio-medical print has grown at the fastest rate, followed by industrial uses of 3D printing. According to the Future of Industrial Decoration and Printing, printed electronics will lead the growth in coming years as the promise of the technology finally comes to market. Going forward, the lowest growth sector will be for promotional decoration and a broad sector of miscellaneous products, but even this is forecast to be positive.
According to the report, screen printing is the most widely used process in 2013 and this will continue as many suppliers have come to rely on the simple, flexible processes. It is commonly used in both web and sheet forms, and is much used to print individual items. The capability of the process to deposit thick films of functional inks is providing good value growth prospects going forward as new printed electronic products reach the market.
Regionally, Asia is rapidly becoming the major region for industrial printing with strong growth across all processes and applications. In 2018, Asia will account for 43% of all global industrial print, up from 38.8% in 2013. The prospects for industrial printing are also strong in both Western Europe and North America.
The importance of industrial printing is growing for equipment and consumable suppliers as several commercial sectors are declining and markets are coming under pressure. Many of the leading inkjet head, equipment and ink suppliers are developing new solutions which will shape the future of the industrial printing sectors.
The Future of Industrial Printing and Decoration to 2018 is available to purchase online and receive immediately for £3950. To find out more about the report and how your company can benefit from a global usage license, please contact: Heather Adams (US) T: +1 207 781 9632 or Stephen Hill (UK) T: +44 (0)1372 802025.

Insight: The Continuously Evolving Specialty Papers Market

Specialty papers serve a wide and diverse range of end uses, many of which have continued to develop and grow, providing many market opportunities for the paper industry. With the declines in graphic markets, the specialty sector has become an area of increasing interest for paper companies whose graphic products are experiencing slumps in demand.
According to Smithers Pira's most recent report on the specialty paper industry, The Future of Specialty Paper Markets to 2018, the global end use market in 2013 was dominated by packaging related applications. For example, flexible packaging, labels and printing related applications, such as inkjet papers and thermal papers. A wide range of other specific applications constituted the other key categories.
The landscape of the specialty paper market is therefore complex and ever-changing. Whether you are a paper mill or are looking to invest in specialty papers, our new bulletin gives you an exclusive insight into the current state of the industry, and what paper mills can do to survive uncertainty.

A shift in decline and expansion

In some markets, the pattern is for a general decline in a particular segment. For example, book printing; perhaps due to an increase in internet-based and electronic readers, and paper filters, which are losing share to polyester filters in automotive applications.
In contrast, some segments have benefitted from changes in retail and manufacturing technology which have improved their prospects. Labels and release liners are now increasingly necessary; coffee and tea bags have been expanding their share, replacing traditional loose-fill; and the emphasis on reducing air pollution has increased demand for industrial filtration.
In some areas, such as electrical applications, specialty papers are used in infrastructure. Therefore consumption is clearly higher in the developing world and stagnant in the developed world. Similarly, security papers, currency, cheque paper and postage stamp paper are growing in emerging areas but remain static in more developed ones. The use of specific specialty papers is universal in other segments, so gift-wrap papers, glassine and crepe papers have buoyant consumption levels in all markets.

Continuous market growth is not assured

The diverse nature of the specialty paper industry is reflected in the variations of growth rates observed for different end use products. Specialty paper is misleadingly synonymous with the ability to generate high growth rates; while some grades perform well with sustained annual growth rates, this may be due to a switch in technology favouring this grade. The reality is that many specialty paper grades have a shorter production lifespan than commodity papers, and this is to be expected where specialty grades are developed in conjunction with evolving technologies. Many grades which once showed high growth are now almost extinct, including dielectric coated, thermal fax paper, tabulating cards and carbon paper.
In some cases, the growth of specialty paper is related to fashion trends, such as wallpapers, (décor changing from painted walls to the use of paper or plastics or textile wall coverings); others are influenced by changes in health concerns (cigarette papers, filtration); and others by changes in economic development (filtration grades introduced where no filtration existed before building and construction grades).

The impact of mergers and acquisitions

In production terms, Europe accounted for almost half of all production in 2013 with North America and Asia generating most of the remainder. With the diversity of products, no paper supplier has greater than 5% share of the specialty paper market. In addition, the specialty sector, although thriving in many end use markets, has not been immune from the commercial and economic factors affecting the paper sector as a whole.
Mergers, acquisitions and the development of operational alliances have grown in number, for example, the formation of Expera Specialty Solutions through a merger of Wasau Specialty Paper and Thilmany. The combination of these mergers and other players looking to enter the arena is making the space more competitive for all.

How can paper mills survive?

For mills to survive in this increasingly competitive market, the future has to lie in retaining a premium image, maintaining flexible production and cultivating strong relationships with converters who have most direct contact with end users.
Additionally, product development has to be continuous to ensure products meet the ever-demanding needs of a diverse customer base. The part of third party technology providers will increase to enable paper products to evolve and compete more effectively with alternative materials and substrates.
If you want to know more about the future of the specialty papers market, purchase our new report, The Future of Specialty Paper to 2018 now.

Global Personal Care Packaging Industry to reach $28.2 Billion by 2018

The global personal care market is projected to be worth 421.2 billion in 2012 and is forecast to grow during the period 2013-18 at a CAGR of 4.9%, according to a new market report by Smithers Pira.
To examine the reasons behind this growth, Smithers Pira have produced a new market report, The Future of Personal Care Packaging to 2018. This new study analyses the global market for personal care packaging, including cosmetics and toiletries. The report focuses particularly on the overall personal care industry, and provides data on personal care packaging markets by world region, including market value forecasts through to 2018 for 13 major countries.
According to The Future of Personal Care Packaging 2018, there are a number of drivers and trends driving packaging demand. These include brand owners reacting to a consumer requirement for more environmentally-friendly products and packaging by using more natural ingredients and recycled packaging. The report also states that ageing populations and the growing popularity of male grooming are key factors.
In terms of geography, the US is the largest national market for personal care packaging, with a 14.8% total market share in 2012. Japan is the second largest national market, followed by Brazil and China. Asia-Pacific is the largest regional market with one-third of global value, followed by Western Europe and North America. India, China and Brazil are the fastest growing countries, and China is set to become the world's largest personal care packaging market during the forecast period. North America, Western Europe and Japan are relatively mature markets and are forecast to show below-average growth rates.

According to the report, rigid plastic is the most used material for packaging personal care products, accounting for over half of the total market value in 2012. This material is also used to produce pumps, sprays and other closing fixtures. Glass is the second largest material category, followed by flexible packaging and board. Rigid materials are expected to continue to grow at a rate above market average during the forecast period, while metal is forecast to experience the lowest growth.
Figure E.1 Global personal care packaging: percentage market share of market value by material, 2012
When it comes to pack types, plastic bottles are set to outperform all others, according to the new report. Plastic bottles and jars account for the largest share of personal care packaging with 27.8% of total market value in 2012. Cosmetics cases and pumps and sprays are also forecast to grow ahead of the market average rate. On the other hand, metal containers are expected to lose further market share.
Skincare is the biggest product category within personal care packaging, accounting for a value share of 22.6% in 2012. This growth will be driven by a growth in demand for facial care and anti-aging products in particular. Hair care and colour cosmetics are the next largest sectors with respective value shares of 19.0% and 18.9%.
The Future of Personal Care Packaging is available now for £3,555 until the 31st of January. To find out more about the report and how your company can benefit from a global usage licence, please contact: Heather Adams (US) T: +1 207 781 9632 or Bill Allen (UK) T: +44 (0)1372 802086.